Rolling an old 401(k) into an IRA can be a reasonable next step after leaving a job or retiring.
It can simplify your accounts, expand your investment options, and make your retirement assets easier to manage.
But if your 401(k) includes highly appreciated employer stock, it may be worth slowing down before you complete the rollover.
There is a tax strategy called Net Unrealized Appreciation, or NUA, that can sometimes change how the growth in that employer stock is taxed.
And once the stock is rolled into an IRA, that opportunity may be gone.
What Is Net Unrealized Appreciation?
Net Unrealized Appreciation is the difference between what the employer stock originally cost inside the retirement plan and what it is worth when it is distributed.
Consider a simple example.
Suppose your 401(k) includes employer stock with:
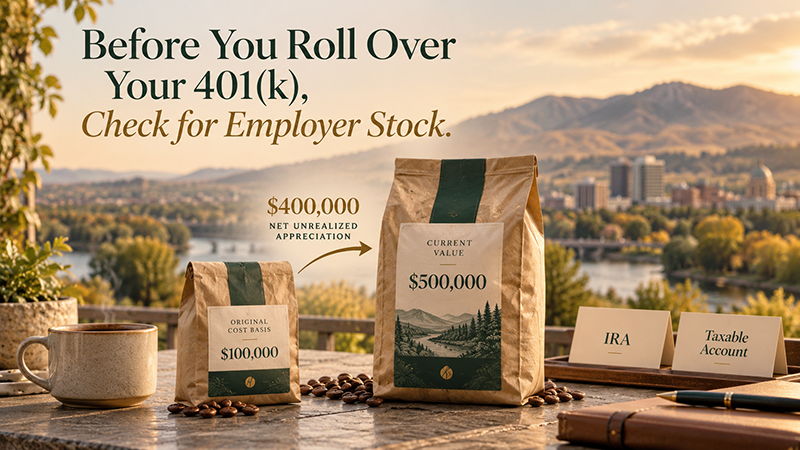
- Original cost basis: $100,000
- Current value: $500,000
The difference — $400,000 — is the Net Unrealized Appreciation.
If you simply roll the shares into an IRA, future distributions from the IRA are taxed as ordinary income.
But under certain circumstances, you may instead be able to distribute the employer stock into a taxable brokerage account.
That can create different tax treatment.
How the Tax Treatment Can Differ
Using the same example:
- Cost basis: $100,000
- Current value: $500,000
- NUA: $400,000
If the shares qualify for NUA treatment and are distributed to a taxable account, the $100,000 cost basis is generally taxed as ordinary income in the year of distribution.
The $400,000 of NUA is generally not taxed until the shares are sold, and when it is sold, that appreciation can qualify for long-term capital-gains treatment.
That distinction matters because long-term capital-gains tax rates are lower than ordinary income-tax rates.
So instead of eventually paying ordinary income tax on the entire $500,000 as it comes out of an IRA, the $400,000 of NUA can receive long-term capital-gains treatment.
That can be valuable.
But it does not automatically mean NUA is the better strategy.
NUA Is Not Just a Tax-Rate Comparison
It is easy to look at the example and conclude:
“Capital-gains rates are lower, so NUA must be better.”
But that skips over several important tradeoffs.
For one, using NUA generally means recognizing ordinary income on the cost basis now rather than continuing to defer it inside a retirement account.
You also need to consider what happens to the stock after it enters the taxable account.
If a large portion of your retirement savings is concentrated in one company, the tax benefit of NUA has to be weighed against the investment risk of continuing to hold that stock.
Diversification may matter more than preserving every possible tax advantage.
Your age, cash-flow needs, tax bracket, state taxes, Medicare premiums, charitable plans, and estate-planning goals can all affect whether NUA makes sense.
In other words, this is not simply a tax decision.
It is a retirement-income, investment, and tax-planning decision all at once.
The Rules Matter
NUA treatment is subject to specific rules.
In general, it involves distributing employer securities in kind from a qualified retirement plan rather than rolling those shares into an IRA.
Certain triggering events and distribution requirements may also apply.
The details can be complex enough that this is not a strategy to implement casually.
The important point is not that everyone with employer stock should use NUA.
The important point is that you should know whether the opportunity exists before you make an irreversible rollover decision.
Why Timing Matters
This is where NUA fits the broader theme of retirement decisions that deserve planning before you act.
A 401(k) rollover can feel routine.
You leave a company, open an IRA, and move the account.
But if employer stock is included in the plan, the rollover itself can eliminate a planning option you may have wanted to evaluate first.
Once the employer shares are rolled into an IRA, the NUA opportunity for those shares is lost.
That means the best time to ask about NUA is before the rollover is completed.
A Better Question Before You Roll Over
Instead of only asking:
“Where should I move my 401(k)?”
Ask:
“Are there any tax or planning opportunities inside this account that I could lose by moving it?”
For many people, the answer may still be to roll the account into an IRA.
But that decision is stronger when it is made after understanding the alternatives.
Retirement planning is often less about finding one universally correct answer and more about identifying the tradeoffs before the choice is made.
NUA is a good example of that.
Van Nostrand Wealth Management is an independent, fee-only fiduciary wealth management firm helping families coordinate retirement, tax, investment, and estate-planning decisions.
Learn more at vnwealth.com.
This article is for educational purposes only and should not be considered individualized investment, tax, legal, or retirement-plan advice. NUA rules are complex, and the examples used here are hypothetical and may not reflect the tax treatment applicable to any specific person.