Most financial decisions can be changed later.
If an investment no longer fits your plan, you can sell it. If your spending changes, you can adjust. If your financial situation evolves, your plan can evolve with it.
But some retirement decisions are different.
They may not be completely irreversible, but changing course later can be difficult, expensive, or sometimes impossible. That makes the planning that happens before the decision especially important.
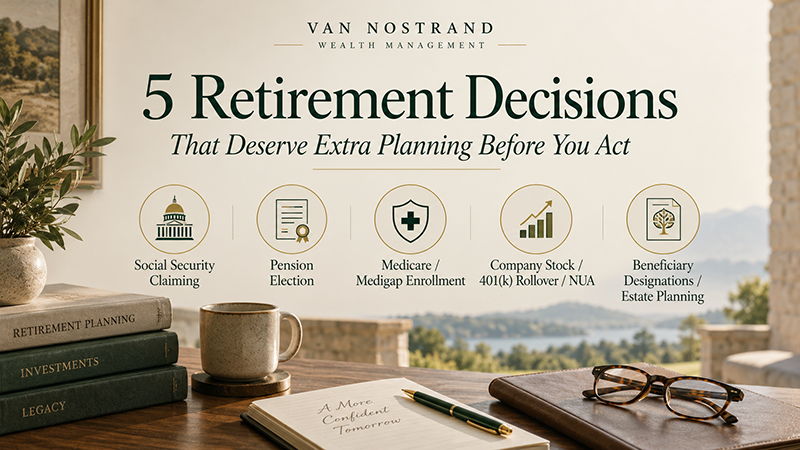
Here are five retirement decisions that deserve extra attention before you act.
1. When to Claim Social Security
For many retirees, Social Security is one of the largest guaranteed income sources they will have.
The question is often:
Should I claim at 62, at full retirement age, or wait until 70?
A breakeven calculation can be helpful. It tells you how long you would need to live for delaying benefits to produce more total income than claiming earlier.
But that is only part of the decision.
For married couples, Social Security is often less about finding the “best” claiming age for each person individually and more about how the two decisions work together.
Consider a hypothetical couple, Marshall and Lily.
Marshall is 67 and was the higher earner during their careers. Lily is 64 and had lower lifetime earnings.
Suppose Marshall’s Social Security benefit at full retirement age (FRA) is $3,500 per month and Lily’s benefit at FRA is $2,100 per month. If they each wait until 70, their benefits increase to $4,340 and $2,604, respectively.
At first glance, Marshall might compare claiming now versus waiting until 70 using a simple breakeven calculation and decide he isn’t likely to live long enough for delaying until 70 to make sense.
But that misses an important issue: Lily’s survivor benefit.
If Marshall dies first, Lily may eventually be eligible to receive a survivor benefit based on Marshall’s record. If Marshall claimed at 67, Lily’s survivor benefit would be $3,500. But if Marshall had waited until 70, Lily’s survivor benefit would have been $4,340.
That means Marshall’s claiming decision is not only about how much income he receives while he is alive. It may also affect Lily’s income for the rest of her life after his death. That changes the entire breakeven calculation.
Meanwhile, Lily may have a different claiming decision. If she is the lower earner, waiting until 70 may increase her benefit to $2,604, but her survivor benefit would be unaffected by whether she claimed her own benefit at 67 or 70. Assuming Marshall filed at 70, that means a $4,340 survivor benefit either way.
So instead of simply asking:
“At what age do I break even?”
Individuals, especially married couples, should understand the impact and tradeoffs that each claiming strategy has before making that decision.
2. Which Pension Option to Choose
If you are fortunate enough to have a pension, you may face a decision that is difficult to change once payments begin.
For example, you might be offered:
- $4,500 per month for your lifetime only
- $4,000 per month with a survivor benefit for your spouse
- A lump-sum payout instead of monthly income
It is tempting to simply choose the option with the highest monthly payment or take the lump sum and invest it.
But much like Social Security, the right answer depends on the rest of your financial situation.
A pension can serve as a valuable source of predictable income, especially during periods when the stock market is down. A survivor option may also provide important protection for a spouse who could outlive the pension recipient.
There is rarely a cut-and-dried right answer. Rather, there are tradeoffs with each option, and those tradeoffs should be understood in the context of the entire retirement plan before making the election.
3. Medicare and Medigap Enrollment Decisions
Medicare is another area where timing matters.
If you are still working at age 65, or covered under a spouse’s employer health plan, you may have delayed certain parts of Medicare without penalty.
But the rules depend on the type of coverage you have.
Missing the proper enrollment window can potentially lead to gaps in coverage or late-enrollment penalties.
Medigap also has an important timing component.
Under federal rules, most people have a six-month Medigap open enrollment period that begins when they are age 65 or older and enrolled in Medicare Part B.
During that window, insurers generally cannot deny you a Medigap policy or charge more because of health conditions.
After that period ends, switching to Medigap may be more difficult depending on your health, your state, and your circumstances.
That does not mean one Medicare path is always better than another.
It means your first decision deserves more attention than simply asking which plan has the lowest premium today. And it means you should have a plan in place for this decision before you reach age 65.
4. What to Do With Company Stock Before Rolling Over a 401(k)
Rolling an old 401(k) into an IRA can be a perfectly reasonable decision.
But if your 401(k) contains highly appreciated employer stock, you may want to slow down before completing the rollover.
A strategy known as Net Unrealized Appreciation, or NUA, can sometimes allow the appreciation in employer stock to receive long-term capital-gains tax treatment rather than eventually being taxed entirely as ordinary income.
For example, imagine company stock inside your 401(k):
- Original cost basis: $100,000
- Current value: $500,000
- Appreciation: $400,000
Under certain rules, you may be able to distribute the employer shares into a taxable account instead of rolling them into an IRA.
The $100,000 cost basis is generally taxed as ordinary income, while the $400,000 of NUA may qualify for long-term capital-gains treatment when the shares are sold.
That does not automatically make NUA the right strategy.
Taxes, diversification, concentration risk, age, cash-flow needs, state taxes, and other factors all need to be considered.
The important part is timing.
Once employer shares are rolled into an IRA, the NUA opportunity for those shares is lost.
So before completing a rollover, it is worth asking:
“Are there any planning opportunities I could be giving up?”
5. How to Structure Beneficiary Designations
Beneficiary planning is often treated as an administrative task.
Make sure the right names are listed on your IRA, 401(k), Roth IRA, life insurance policies, etc., and move on.
But there can be more to it than that.
The question is not only:
“Who gets my money?”
It can also be:
“Which assets should each beneficiary receive?”
Different assets can have very different tax consequences.
For example, a traditional IRA generally creates taxable income for children when they withdraw the money.
A Roth IRA may be much more tax-efficient for them.
Taxable investments may receive a step-up in cost basis at death, which can also make them more attractive assets to leave to family.
Even among children, tax situations may differ.
If one child is in a much higher tax bracket than another, it may sometimes make sense to leave more tax-efficient assets to the higher-earning child and more tax-deferred assets to the lower-earning child, while still trying to create an economically fair result.
Beneficiary planning should be coordinated with the rest of your estate and tax plan, not simply divided account by account.
The Common Thread
These five decisions are very different.
Social Security, pensions, Medicare, 401(k) rollovers, and beneficiary designations all have their own rules.
But they share one important characteristic:
The planning is most valuable before the decision is made.
Retirement planning is not only about choosing investments or deciding how much you can spend.
It is also about identifying the decisions ahead of time, understanding the tradeoffs, and making sure one financial decision does not unintentionally create a problem somewhere else.
That is where coordinated planning can make a meaningful difference.
Van Nostrand Wealth Management is an independent, fee-only fiduciary wealth management firm helping families coordinate retirement, tax, investment, and estate-planning decisions.
Learn more at vnwealth.com.
This article is for educational purposes only and should not be considered individualized investment, tax, legal, or Social Security advice. Examples are hypothetical and may not reflect the rules or outcome applicable to any specific person.